

08 Nov 2017
Taxation on P to P Lending
By the end of October 2017, Financial Service Authority (OJK) has issued 25 STBD (Letter on Registration Document) for 25 Peer to Peer (P to P) lending companies.
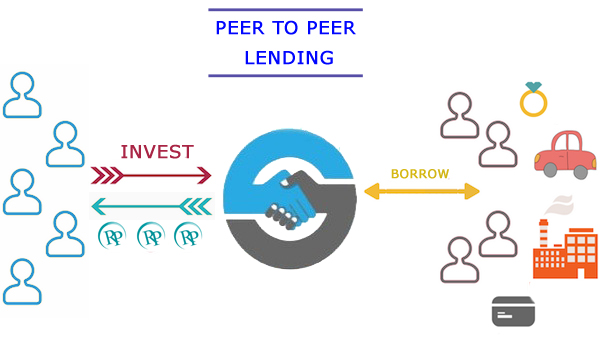
Fintech created transaction for investor and borrower via online for P to P lending.
In general, interest and commission are the natures of income earned that happened in this P to P lending.
By income tax law regulations, interest that paid to the investors will be subject to withholding tax. By the end of the year, the recipient should recalculate the interest income to the all over taxable income during the year and it will be subject to the progressive tax rate.
I believe Bank Indonesia (BI) will regulate the license of this P to P. It is interesting issue if P to P lending company will be considered as a bank or non bank. If it is considered as a bank, then the withholding tax on interest will be final.
Commission that paid to the marketplace company where they run this P to P lending should be categorized as income that subject to income tax art 23 and progressive tax rate will be applied unless they are a SME.
Best Regards,
Agung Tjahjady SH, CLA, CPA, MM, BKP
Registered Tax Consultant, Advocate
 +62 816 825 348


BVD Oriana User


